Updated August 2026
Pricing AI software hasn’t gotten easier. If anything, 2026 has brought the contradictions into sharper relief. On one side: LLM and generative AI assets with defensible data or inference advantages still pulling 12–20x revenue, sometimes higher when strategic buyers see distribution fit. On the other: enterprise AI applications normalizing back to 3–6x, right where mature SaaS sits when growth moderates and services mix creeps up. The first half of 2026 sharpened the divide. Foundation model marks kept climbing: OpenAI closed a $122 billion round at an $852 billion post-money valuation in March 2026, and Anthropic reached $965 billion in May. The public market repriced applied AI hard over the same stretch: Palantir’s price to sales ratio fell from roughly 119x in September 2025 to about 73x by August 2026, C3.ai lost nearly two thirds of its value in 2026 on shrinking guidance, and SoundHound fell 37%. Deal activity ran the other way. CB Insights counted 266 AI acquisitions closed in Q1 2026, up 90% year over year, and SpaceX agreed to acquire Cursor maker Anysphere for roughly $60 billion in June, the largest startup acquisition on record. For sellers the practical benchmark has not moved with the headlines: FE International puts private AI native software sales at 8 to 15x revenue, with 20x and above reserved for targets holding proprietary data and net revenue retention over 120%. Funding round marks, which pull blended AI medians toward 24x, are a capital raising phenomenon, not sale comps. Windsor Drake’s AI Valuations Q2 2026 and AI M&A Activity Q2 2026 reports track the current quarter in full.
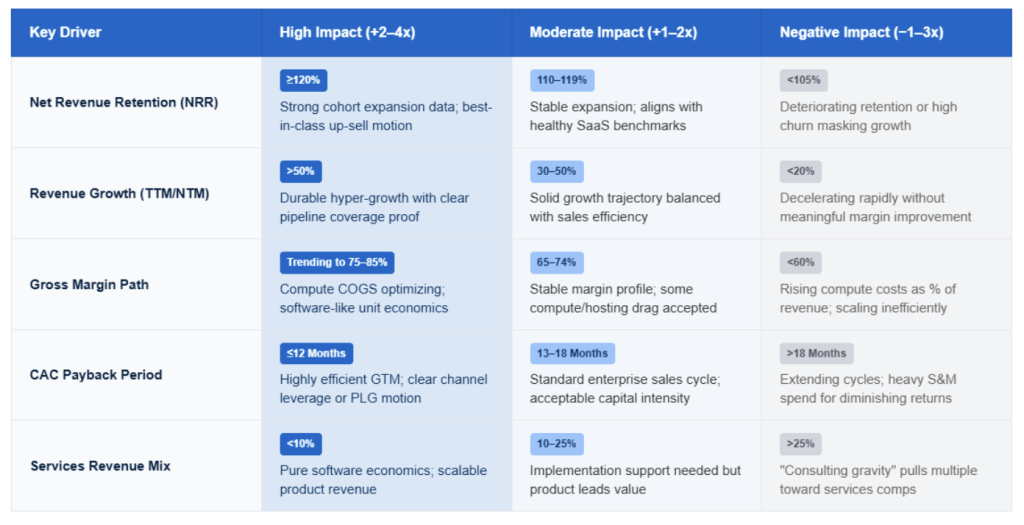
The bifurcation isn’t new, but it widened in Q4 as investors and acquirers separated hype from retention data. Capital moved toward assets where unit economics prove out, not just growth narratives. And the result? Valuation spreads by subsector now exceed historical software ranges. This isn’t a binary AI premium. It’s bracket-by-bracket, stage-by-stage, and increasingly tied to metrics buyers can verify: NRR, gross margin trajectory, compute COGS as percent of revenue, CAC payback. Labels matter less. Numbers matter more.
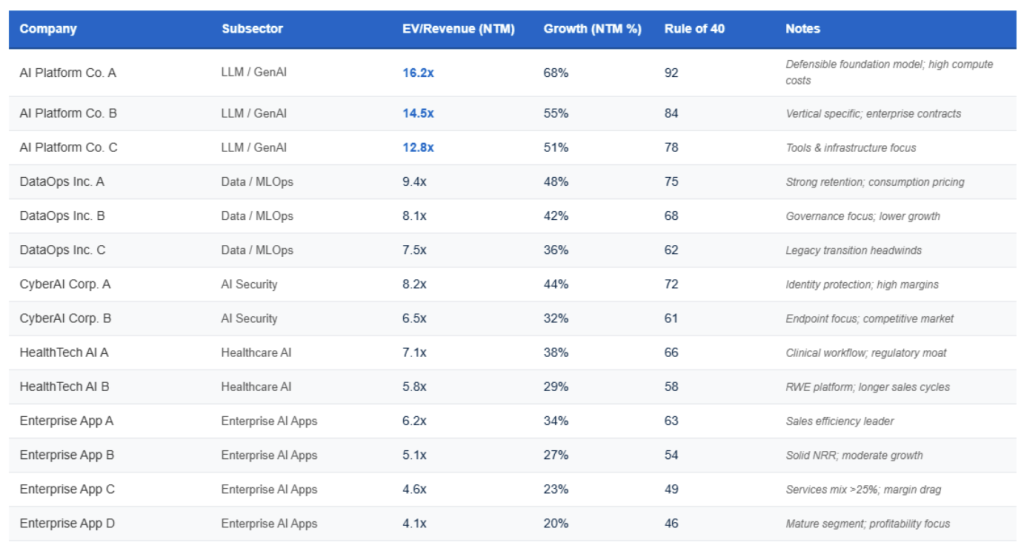
Market multiples dominate live processes (EV/Revenue for growth assets, DCF scenario-weighted when margin paths clear, VC method at early stage). We’re seeing cross-checks via Rule of 40 and precedent transaction ranges bracketing exit assumptions more aggressively.
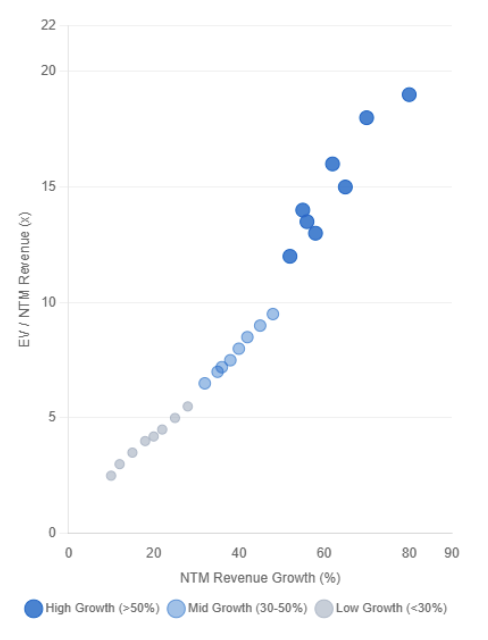
The spread is real: LLM/GenAI cleared at 12–20x (Finro dataset 565 companies); Data/MLOps at 6–9x where lineage/governance attached; Infrastructure-adjacent software held 6–10x. Enterprise AI apps? Back to 3–6x unless retention proof is pristine (<10% services mix and >120% NRR gets you a premium).
Series A still elevated, apps 8–12x, data 15–25x, LLM/GenAI 25–40x if team/IP/traction align. But watch the B/C rounds: spreads widen massively based on GTM efficiency variance. Late/Pre-IPO names converge toward M&A exit comps fast, especially when EBITDA path becomes visible.
North America clears top-end ranges (buyer density, capital depth, acquirer urgency). Europe trails by 0.5–1.0x on comparable profiles, data sovereignty friction and smaller exit universes weigh on multiples. APAC shows wide dispersion; semis/industrial AI command premiums while generalist apps face liquidity constraints. Strategic acquirers pay control premiums where tech stack consolidation is obvious, often 1–2 turns above sponsor bids. Financial buyers stay disciplined around NRR, margin trajectory, and integration lift.
How does this land in practice? Three lenses, depending where you sit.
Show cohorts, not aggregates. Break out NRR by vintage, CAC payback by channel, gross margin with compute COGS called out explicitly. Acquirers and sponsors triangulate, they’ll bracket you with subsector comps and stress-test your DCF assumptions. Clean IP chain and data provenance documentation move you toward the top of the range. Services revenue >20%? Expect questions. Churn masking as growth? Deal-killer.
Anchor to subsector and stage benchmarks, then adjust for quality (Rule of 40, NRR cohorts, margin path). Sensitivity-test NRR ±5 pts and gross margin ±5 pts, those swing multiples more than top-line growth in 12–24 months. Don’t overpay for “AI” labels; underprice defensible data rights at your peril. Buyer universe depth and exit timing matter, especially in thinner categories where liquidity dries up fast.
Pay premiums where distribution fit, data rights, or synergy capture are transparent. Otherwise stay mid-band or walk, particularly if the target’s compute costs or services mix aren’t improving. Strategic rationale has to pencil before you stretch on price. And if integration’s heavy (different stacks, conflicting roadmaps), discount accordingly.