
A scatter of consistently constructed growth cohorts against EV/NTM revenue (cohort growth midpoint plus the basket’s median FCF margin, with the score-40 line marked), a selectable peer table, and the cross-vertical premium from this report. Constituent-level data is licensed and not redistributed, so the chart shows association across cohorts and does not turn correlation into an automatic premium.
The interactive explorer loads here. The default view is published below so the numbers are readable without JavaScript.
Rule of 40 proxy versus EV/NTM revenue, cohort medians: 6.5x at proxy 40. Growth cohort medians from Clouded Judgement, 18 Sep 2026 (public cloud software basket, EV/NTM revenue) (retrieved 2026-09-22) plotted against a Rule-of-40 proxy (cohort growth midpoint plus the basket’s median FCF margin of 21%). Company-level constituent data is licensed and not redistributed, so this is an association across cohorts, not a premium schedule. The Windsor Drake Rule of 40 Premium report found the same score priced at roughly 24x in AI and 5x in SaaS.
| Cohort | Growth basis | Rule-of-40 proxy | Multiple | Source class |
|---|---|---|---|---|
| High growth (>22% NTM) | NTM growth midpoint | 52 | 17.5x | Public trading (median) |
| Mid growth (15-22% NTM) | NTM growth midpoint | 40 | 6.5x | Public trading (median) |
| Low growth (<15% NTM) | NTM growth midpoint | 29 | 3.5x | Public trading (median) |
| 0-10% ARR growth | ARR growth midpoint | 26 | 3.5x | Private and public cohort average |
| 10-20% ARR growth | ARR growth midpoint | 36 | 6.2x | Private and public cohort average |
| 20-30% ARR growth | ARR growth midpoint | 46 | 8.5x | Private and public cohort average |
| 30-50% ARR growth | ARR growth midpoint | 61 | 12.0x | Private and public cohort average |
| >50% ARR growth | ARR growth midpoint | 81 | 16.0x | Private and public cohort average |
Benchmark version 2026.09.22-1. Sources: Clouded Judgement 18 Sep 2026 (growth cohorts, basket medians); SaaS Capital and FinRO cohorts via Windsor Drake; Windsor Drake vertical SaaS public comps (Aug 2026); this report (June 2026).
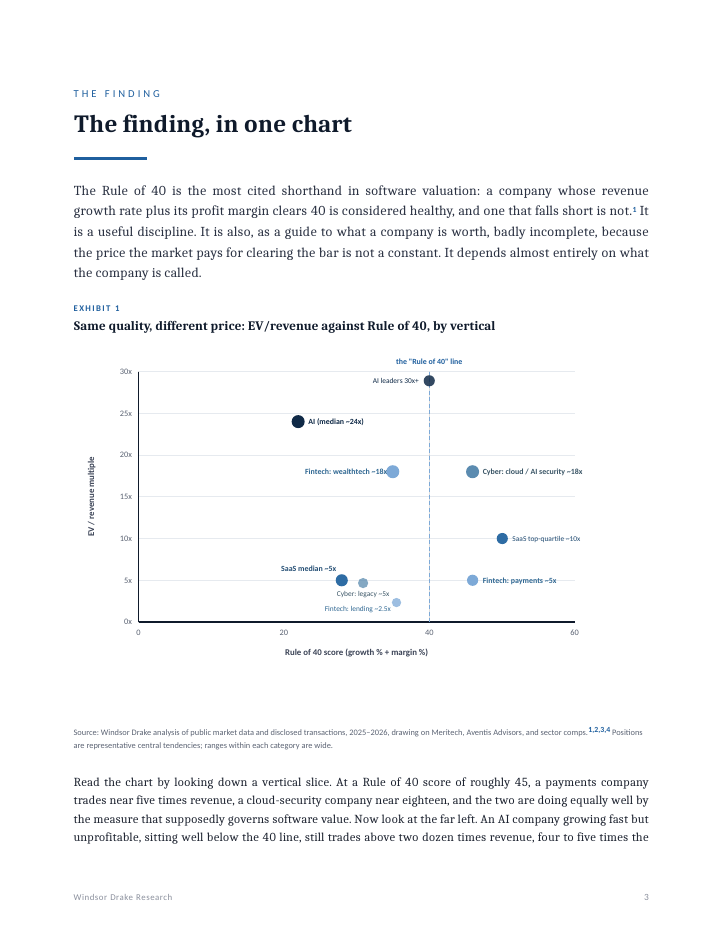
The Rule of 40 is the most cited shorthand in software valuation: a company whose revenue growth rate plus its profit margin clears 40 is considered healthy, and one that falls short is not.1 It is a useful discipline. It is also, as a guide to what a company is worth, badly incomplete, because the price the market pays for clearing the bar is not a constant. It depends almost entirely on what the company is called.
Before the rule can be useful, it has to be understood for what it is: a single number that compresses two of a company’s most important traits into one, and in doing so throws away most of what determines value.
Each vertical values software on its own scale. The four benchmarks below establish where each market clears today and how quality moves the number inside it. Read together, they make the cross-vertical premium in Part III impossible to miss.
With each vertical’s scale established, the cross-cut becomes arithmetic. Take a company sitting exactly at the Rule of 40, the same quality by the standard measure, and ask what it is worth in each market. The answer is the premium this report set out to size.
A benchmark is a photograph of a market in motion. The relationships in this report are stable in structure but shifting in magnitude, and a seller timing a process needs to know which way each base is trending.
If two companies post the same Rule of 40 and trade at multiples five times apart, the difference is not in the score. It is in four things the score cannot see. Each one moves the base multiple, and together they explain the dispersion in Exhibit 1.
Windsor Drake’s research desk compiled this report from transaction data, public filings, and the firm’s sell-side advisory work in software, fintech, AI, and cybersecurity. It is intended to inform founders, owners, and acquirers evaluating a transaction, and does not constitute investment advice.
A look at the exhibits and analysis inside. The complete report is free to read, with no registration required.
The complete report is open. No registration required.
Open the report (PDF)Used only to deliver the report and occasional research. No spam. Unsubscribe anytime.
Why the same growth is priced four ways. The Rule of 40 is the most cited shorthand in software valuation: a company whose revenue growth rate plus its profit margin clears 40 is considered healthy, and one that falls short is not.
The report draws on 2025 deal activity across the software, fintech, AI, and cybersecurity markets, with Windsor Drake’s outlook for 2026.
It is complimentary. The full report is open on this page as a PDF, with no registration required.
Founders, owners, and shareholders weighing a sale, alongside the acquirers, investors, and journalists who track lower middle market M&A.
For founders acting on these findings, Windsor Drake’s SaaS valuation multiples sets out the detail in practice. The full series is collected in the Windsor Drake Insight Reports library. Read the Rule of 40 explainer.
Windsor Drake advises founders directly on fintech M&A, cybersecurity M&A, and SaaS valuation.
Our research desk publishes the data founders and acquirers actually use. Browse the full library, or speak with us in confidence.
Explore all researchWindsor Drake represents founders on the sell side only. Every inquiry is read and answered personally, usually within one business day, and every conversation is confidential and without obligation.
Discuss a potential saleWindsor Drake is not a registered broker-dealer and does not offer, sell or place securities.